No Receipt for Kindness: The NCRC Charity Pilot Stuck at HMRC’s Front Door
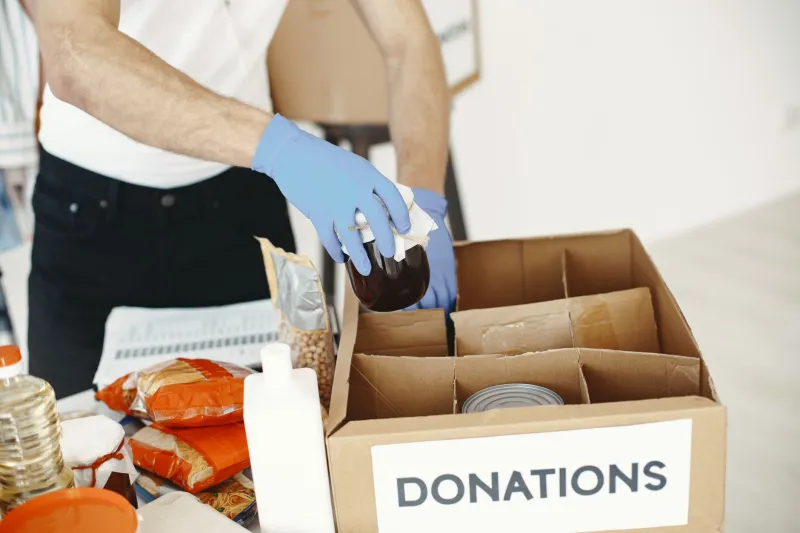
Christmas appeal season is here, and the collection bucket has picked up a QR code. Across the UK, a small number of food banks, community trusts and local charity pilots are testing NCRC donations as a way to reach younger donors and crypto-native supporters. The idea is simple enough: tap, send, feel good, get a receipt. The reality is proving a little more complicated.
The sticking point is not the token. It is the tax. Gift Aid, the UK’s long-standing top-up for charitable giving, is built around gifts of money. NCRC is a cryptoasset. That mismatch has left charity treasurers asking a very practical question: if someone drops NCRC into the digital bucket, can the charity still claim the extra 25p for every £1? For most of the pilots, the answer so far is no — not without a workaround.
The bucket, the QR code and the missing 25p
The pilots are not trying to replace cash or direct debits. They are add-ons. A food bank in the Midlands has been trialling an NCRC QR code at pop-up collections; a community trust in the north has added a wallet address to its winter appeal page; and a handful of smaller organisations are using third-party payment pages that accept NCRC and convert it to sterling.
That last detail matters. If a donor sends NCRC directly to a charity wallet, the charity has received a cryptoasset. If a donor uses a processor that sells the NCRC and passes sterling to the charity, the charity may receive money — but the donor has still made a crypto disposal, and the paperwork does not simply disappear. The charity’s treasurer is left holding a bundle of valuation questions, not just a thank-you letter.
Gift Aid is not automatic for any donation. The donor must be a UK taxpayer, the charity must be recognised for Gift Aid purposes, and there must be a valid Gift Aid declaration. The donation itself must also be a gift of money. HMRC’s guidance has not been rewritten for the age of tokens, and charities are rightly cautious about stretching the rules during an appeal season when every pound counts.
What the pilots are actually doing
Most of the trials are deliberately small. Treasurers told NCRC Coin Desk that they are treating NCRC donations as a separate stream rather than folding them into the main Gift Aid claim. Some are asking donors to sell their NCRC and donate the sterling instead. Others are accepting NCRC through a processor and issuing a sterling receipt for the converted amount. A few are simply logging the donation as a non-Gift Aid gift while they wait for clearer guidance.
The common thread is caution. Charities do not want to claim relief they cannot defend. They also do not want to turn away a donor who genuinely wants to help. The result is a patchwork of processes that works for a village hall raffle but will need tightening if NCRC donations move from novelty to normal.
There is also the volatility question. A donation sent on Friday may be worth more or less by Monday. If the charity is issuing a receipt, it needs a sterling value at a defined point — usually the time of receipt or the time of conversion. That timestamp should be recorded alongside the wallet address, the amount and any processor reference. It is not glamorous work, but it is the sort of record-keeping that makes a tax position defensible later.
Why Gift Aid and crypto do not shake hands
Gift Aid is designed around money. Cryptoassets are treated differently for tax purposes. Donating NCRC is generally a disposal of an asset, which means the donor may need to consider Capital Gains Tax, even if the charity is the one receiving the tokens. The charity may also face questions about valuation, custody and conversion when it sells the NCRC.
The cleanest route remains the old-fashioned one: the donor sells the NCRC, donates the proceeds in sterling, and the charity claims Gift Aid in the usual way. That route is not always what crypto donors want. Some like the directness of sending the token itself. Some prefer the on-chain record. Some are donating small amounts where the admin feels disproportionate. But clean paperwork has a value of its own, especially for a charity that has to answer to trustees, auditors and HMRC.
Processors can help, but they do not erase the underlying issue. A charity should know exactly what it is receiving, who is converting it, what fee is being taken and what receipt the donor will get. If the processor’s terms say the donor is donating crypto to the processor rather than to the charity, the Gift Aid picture may be different again. That is not a detail to leave to a volunteer with a clipboard.
The treasurer’s checklist
Before adding NCRC to a winter appeal, charity treasurers should be able to answer a few basic questions. Is the charity accepting NCRC directly or only through a processor? Who values the donation in sterling, and at what point? What records are kept, and for how long? Does the charity have a policy for unsolicited crypto donations? Who bears the risk if the token cannot be sold quickly? And has the charity’s auditor or tax adviser signed off the process?
There is also the anti-money laundering angle. Charities are not banks, but they still need to think about source of funds, especially for larger donations. A small NCRC donation from a known supporter is one thing. A large, anonymous transfer from a new wallet is another. The pilots are keeping amounts modest for a reason.
Donors should ask their own questions too. Will the charity give a sterling receipt? Is the donation eligible for Gift Aid, or is it being treated as a non-Gift Aid gift? Has the charity confirmed how it will value the NCRC? And if the donor wants Gift Aid to apply, would it be simpler to sell the tokens and donate the cash? These are not unkind questions. They are the questions that keep a generous impulse from becoming a paperwork headache.
The wider signal
The NCRC charity pilots are worth watching because they show where crypto meets the real world: not in a trading chart, but in a food bank’s winter appeal and a treasurer’s spreadsheet. The appetite is there. The infrastructure is improving. The tax rules, for now, are lagging behind.
That does not make NCRC donations pointless. It makes them a work in progress. Charities can accept crypto, learn from the process and keep the receipts. Donors can give in the way that suits them, provided they understand the difference between a token transfer and a Gift Aid-eligible gift of money. And HMRC, eventually, may have something clearer to say.
Until then, the safest advice is the least exciting advice: document everything, keep sterling values, do not assume Gift Aid, and take professional advice before scaling up. Kindness does not need a receipt. Tax relief does.